Five months ago, the Stock Trends data showed an unusual development. Favorable forward-return distributions were expanding beyond established Bullish trends and appearing in Weak Bullish, consolidation, and even selected Bearish configurations. The implication was that probability was improving before conventional trend confirmation.
The September 18 dataset tells the next chapter of that story. Forward probability has not continued to disperse across trend states. It has moved back toward Bullish structures, particularly among broad-market ETFs. Yet the common-stock universe beneath those indexes has barely become more bullish at all.
Five Months Later, Breadth Has Barely Moved
The most important comparison with April is not the level of the major indexes. It is the internal trend distribution of the stock market.
In early April, 45.7% of the comparable common-stock universe occupied the Bullish trend family, while 41.5% occupied Bearish classifications. In the September 18 dataset, those numbers are 46.6% Bullish-family and 41.3% Bearish-family.
| Stock Trends Classification | April 2026 | September 18, 2026 | Change |
|---|---|---|---|
Bullish ( ) |
31.6% | 29.7% | -1.9 pts |
Weak Bullish ( ) |
13.4% | 16.0% | +2.6 pts |
Bullish Crossover ( ) |
0.7% | 0.9% | +0.2 pts |
| Neutral (--) | 12.9% | 12.1% | -0.8 pts |
Weak Bearish ( ) |
4.6% | 7.3% | +2.7 pts |
Bearish ( ) |
35.1% | 32.7% | -2.4 pts |
Bearish Crossover ( ) |
1.8% | 1.3% | -0.5 pts |
That is an unexpectedly small change over more than five months.
There are fewer stocks in fully confirmed Bullish trends than there were in April. At the same time, both Weak Bullish and Weak Bearish classifications have expanded. In other words, more stocks are occupying transitional structures rather than joining a synchronized market advance.
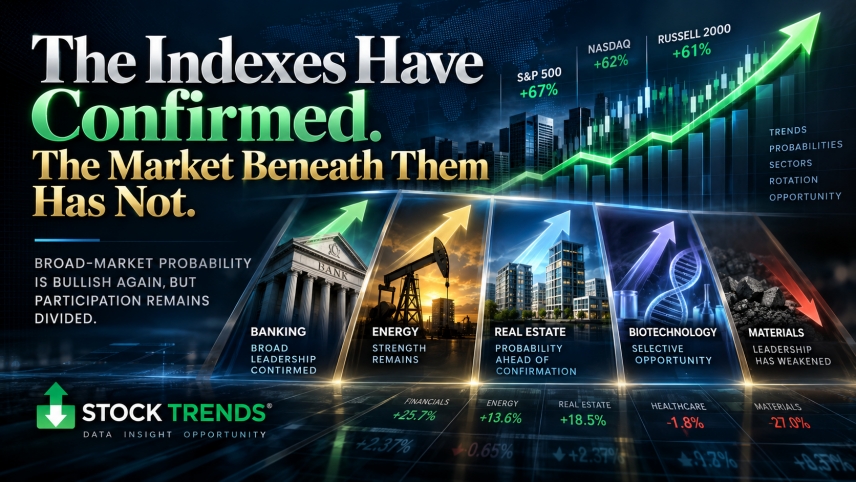
This is the first important distinction in the current market: the indexes have strengthened much more convincingly than the underlying common-stock breadth.
The Indexes Are Telling a Different Story
The major Stock Trends index records are firmly Bullish. The S&P 500 is in a 25-week Bullish trend with an RSI of 100. The NYSE Composite is also 25 weeks Bullish with an RSI of 100. The S&P/TSX Composite has reached 26 weeks Bullish, while the Nasdaq Composite remains Bullish as well.
The Stock Trends Inference Model reinforces that index-level strength through broad-market ETFs.
| ETF | Symbol | Trend | 13-Week Outperformance Probability |
|---|---|---|---|
| Vanguard S&P 500 ETF | VOO | Bullish | 67.31% |
| State Street SPDR S&P 500 ETF Trust | SPY | Bullish | 62.54% |
| iShares Russell 3000 ETF | IWV | Bullish | 62.62% |
| Schwab U.S. Broad Market ETF | SCHB | Bullish | 62.62% |
Among the 67 ETFs currently meeting the final ST-IM Select probability threshold, 62 are already in established Bullish trends. That is more than 92% of the ETF Select population.
This represents a significant change from the structure highlighted in April. At that time, the most interesting message from the model was that favorable probability distributions were appearing outside confirmed Bullish trends. Today, at the broad-market level, probability and trend have largely reconverged.
Forward Probability Has Reconnected With Trend
The ST-IM Select framework requires more than a positive expected return. The lower limit of the historical forward-return confidence interval must exceed the appropriate random-return baseline at all three primary horizons: 0.00% at four weeks, 2.19% at 13 weeks, and 6.45% at 40 weeks. Stocks meeting those conditions are then ranked by the probability that their 13-week forward return will exceed the 2.19% baseline, with a minimum probability of 55% for the Select designation.
There are currently 390 comparable common-stock observations with qualifying distributions across all three horizons. Their trend composition is revealing.
Of those 390 observations, 302 are Bullish and another 77 are Weak Bullish. That means 97.2% of the qualifying probability population is now concentrated in those two Bullish trend states.
Apply the final 55% 13-week probability requirement and the concentration remains clear. Of 77 current common-stock Select observations, 39 are Bullish and 30 are Weak Bullish. Nearly 90% of the final Select population is therefore Bullish or Weak Bullish.
The probability signal has not disappeared. It has become more aligned with trend.
That makes the remaining exceptions particularly interesting. Noble Corporation plc (NE), currently in a Bearish Crossover classification, carries the highest common-stock 13-week probability in the dataset at 71.97%. United Therapeutics Corporation (UTHR), also classified as a Bearish Crossover, follows at 70.32%.
Those names demonstrate that the model can still identify a favorable historical distribution before trend confirmation. But today they are exceptions. In April, that phenomenon was part of the broader market structure.
The Bigger Change Is Where Leadership Has Moved
If overall breadth has changed very little, the next question is obvious: where has the strength gone?
The answer is rotation.
The April market was distinguished by strong Materials and Energy structures, with secondary leadership developing in groups such as Banking. Five months later, Banking has moved decisively into the leadership position. Energy remains strong. Real Estate has developed a particularly interesting transitional structure. Materials, by contrast, has weakened substantially.
| Sector | Bullish-Family | Bearish-Family | Net Breadth |
|---|---|---|---|
| Finance | 60.3% | 34.6% | +25.7 pts |
| Real Estate | 58.6% | 40.1% | +18.5 pts |
| Energy | 54.8% | 41.1% | +13.6 pts |
| Technology | 48.9% | 44.7% | +4.2 pts |
| Industrials | 45.8% | 47.1% | -1.3 pts |
| Healthcare | 46.1% | 47.9% | -1.8 pts |
| Consumer Discretionary | 45.4% | 51.8% | -6.3 pts |
| Media | 41.4% | 54.6% | -13.2 pts |
| Utilities | 38.0% | 58.9% | -20.9 pts |
| Consumer Staples | 37.0% | 58.3% | -21.4 pts |
| Materials | 30.5% | 57.5% | -27.0 pts |
The Materials result is particularly important. The earlier hard-asset leadership theme has not survived as a single bloc. Energy has retained a constructive structure, but Materials has not.
The Stock Trends data is therefore making a distinction that a broad thematic label such as “hard assets” would miss.
Banking: Leadership Has Become Broad and Confirmed
Banking is now the strongest large industry group in the dataset.
Among 382 banking stocks, 85.3% occupy the Bullish trend family. Fully 62.8% are already in established Bullish trends, while just 10.5% fall within the Bearish family. The resulting net breadth spread is an exceptional +74.9 percentage points.
The ST-IM Select population independently reinforces that breadth signal. Thirteen banking stocks meet the current Select threshold, 12 of them Regional Banks.
| Company | Symbol | Trend | 13-Week Probability |
|---|---|---|---|
| Customers Bancorp Inc. (CUBI) | CUBI | Bullish | 62.18% |
| TFS Financial Corporation (TFSL) | TFSL | Weak Bullish | 59.00% |
| UMB Financial Corporation (UMBF) | UMBF | Weak Bullish | 57.87% |
| Royal Bank of Canada (RY) | RY | Bullish | 56.90% |
| Bank of Hawaii Corporation (BOH) | BOH | Weak Bullish | 56.40% |
| Valley National Bancorp (VLY) | VLY | Weak Bullish | 55.56% |
This is no longer secondary leadership beneath a stronger sector theme. Banking itself has become a dominant breadth structure.
There is also an important detail inside the Select list. Several banks are Weak Bullish rather than fully Bullish. The industry therefore combines two characteristics: a large established Bullish population and a second group whose historical probability distributions remain favorable while price structure is consolidating.
Real Estate: Probability Is Ahead of Full Trend Confirmation
Real Estate tells a different story.
The REIT industry group has 72.7% of its stocks in the Bullish family, giving it one of the strongest breadth readings in the market. But only 14.0% are fully Bullish. An extraordinary 58.0% are Weak Bullish.
That distinction matters.
Banking represents established leadership. REITs represent transitional leadership.
The seven current REIT Select observations reinforce that interpretation. Six are Weak Bullish.
| Company | Symbol | Trend | 13-Week Probability |
|---|---|---|---|
| OUTFRONT Media Inc. (OUT) | OUT | Weak Bullish | 59.64% |
| InvenTrust Properties Corp. (IVT) | IVT | Weak Bullish | 57.68% |
| Ventas Inc. (VTR) | VTR | Weak Bullish | 57.59% |
| Lamar Advertising Company (LAMR) | LAMR | Weak Bullish | 56.59% |
| Agree Realty Corporation (ADC) | ADC | Weak Bullish | 55.27% |
| Healthcare Realty Trust Incorporated (HR) | HR | Weak Bullish | 55.16% |
This is very close to the kind of structure the April editorial taught us to look for: probability and positive trend structure appearing before full Bullish confirmation.
The difference is that the phenomenon is no longer spread broadly across the market. It has become concentrated in particular groups such as REITs.
Energy: The Hard-Asset Theme That Survived
Energy has retained much more of its earlier leadership structure than Materials.
Within the Fossil Fuels industry group, 63.8% of stocks are in the Bullish family and 56.7% are already fully Bullish. Only 32.2% are in the Bearish family.
Seven Fossil Fuels stocks meet the current Select threshold.
| Company | Symbol | Trend | 13-Week Probability |
|---|---|---|---|
| Noble Corporation plc (NE) | NE | Bearish Crossover | 71.97% |
| Navigator Holdings Ltd. (NVGS) | NVGS | Bullish | 57.84% |
| Cardinal Energy Ltd. (CJ) | CJ | Bullish | 56.79% |
| Cheniere Energy Inc. (LNG) | LNG | Bullish | 56.46% |
| Shell plc (SHEL) | SHEL | Bullish | 55.90% |
Noble Corporation is particularly informative. Its trend has deteriorated into a Bearish Crossover, yet its historical configuration produces the strongest 13-week probability reading among current common-stock observations. That does not override the trend signal. It tells us that the historical outcome distribution associated with the current configuration remains unusually favorable.
This is exactly why Stock Trends separates descriptive trend information from probabilistic inference.
Biotechnology: Selection Without Broad Leadership
Biotechnology provides the opposite lesson from Banking.
The Biotechnology & Life Sciences industry group is not broadly strong. Only 45.3% of its 642 stocks are in the Bullish family, compared with 48.4% in the Bearish family.
Yet 11 stocks from the group meet the current ST-IM Select threshold.
That is a significant concentration of favorable individual probability structures inside an industry that has not achieved broad trend confirmation.
| Company | Symbol | Trend | 13-Week Probability |
|---|---|---|---|
| United Therapeutics Corporation (UTHR) | UTHR | Bearish Crossover | 70.32% |
| Bicara Therapeutics Inc. (BCAX) | BCAX | Weak Bullish | 61.79% |
| DiaMedica Therapeutics Inc. (DMAC) | DMAC | Bearish | 60.09% |
| Silence Therapeutics plc (SLN) | SLN | Bullish | 58.19% |
| Inhibrx Biosciences Inc. (INBX) | INBX | Bullish | 57.89% |
Biotechnology therefore demonstrates why sector averages alone are insufficient. A mixed industry can still contain a meaningful subset of statistically differentiated securities.
The Select Report Is Also a Market Map
The practical value of this analysis is that Stock Trends subscribers do not need to begin with a macroeconomic forecast or a predetermined sector thesis.
The Stock Trends Inference Model Select Stocks report provides the first filter. Instead of viewing that report only as a ranked list of individual opportunities, investors can examine where those selections cluster by sector, industry and trend classification.
This week's Select population reveals several distinct structures at once. Banking shows broad, mature leadership. REITs reveal a large Weak Bullish transition. Fossil Fuels show continuing established strength. Biotechnology demonstrates selective probability inside an otherwise divided group.
The other Stock Trends Weekly Reporter filters then provide additional context. Top Trending Stocks help identify established momentum. Bullish and Bearish Crossover reports show where classifications are changing. Weak Bullish and Weak Bearish reports reveal transitional structures. Expected-return reports allow the market to be viewed by forward distribution rather than current price trend alone.
This is how the weekly reports can be used together: not merely to find individual stocks, but to reconstruct the market's internal architecture.
What the Market Is Telling Us Now
The September market is stronger than it was in April in one important respect: broad-market trend and forward probability are once again strongly aligned.
But that improvement should not be confused with broad participation.
The common-stock trend distribution has changed surprisingly little. Fully Bullish participation has actually declined modestly. Transitional Weak Bullish and Weak Bearish classifications have increased. What has changed much more substantially is the location of leadership.
Banking has moved from secondary leadership to dominant confirmed breadth. Energy remains the strongest surviving component of the earlier hard-asset structure. REITs show probability developing ahead of widespread Bullish confirmation. Biotechnology continues to reward security selection rather than sector-level generalization. Materials has lost the leadership position it held earlier in the year.
That produces the central message of the current Stock Trends data:
The indexes have confirmed. The probability structure has largely reconfirmed with them. But the market beneath those indexes is still a market of rotation, transition and selective leadership.
Five months ago, the edge was recognizing that probability had begun to move ahead of trend.
Today, the edge is recognizing that broad-market confirmation and broad-market participation are not the same thing.
 I am just writing to tell you of my appreciation of your service! It makes so much sense to me. You seem to be an oasis of stability and sensibility in a stockmarket jungle.